Embedded connectivity in Fintech builds payments, loans and insurance right into the apps you already use, so you never need to visit a bank.
A modern fintech app can do almost everything a traveller needs. It converts currency, issues a virtual card, splits a dinner bill and even buys crypto. But the moment that traveller lands in another country, the app depends on something it doesn’t control: a working data connection.
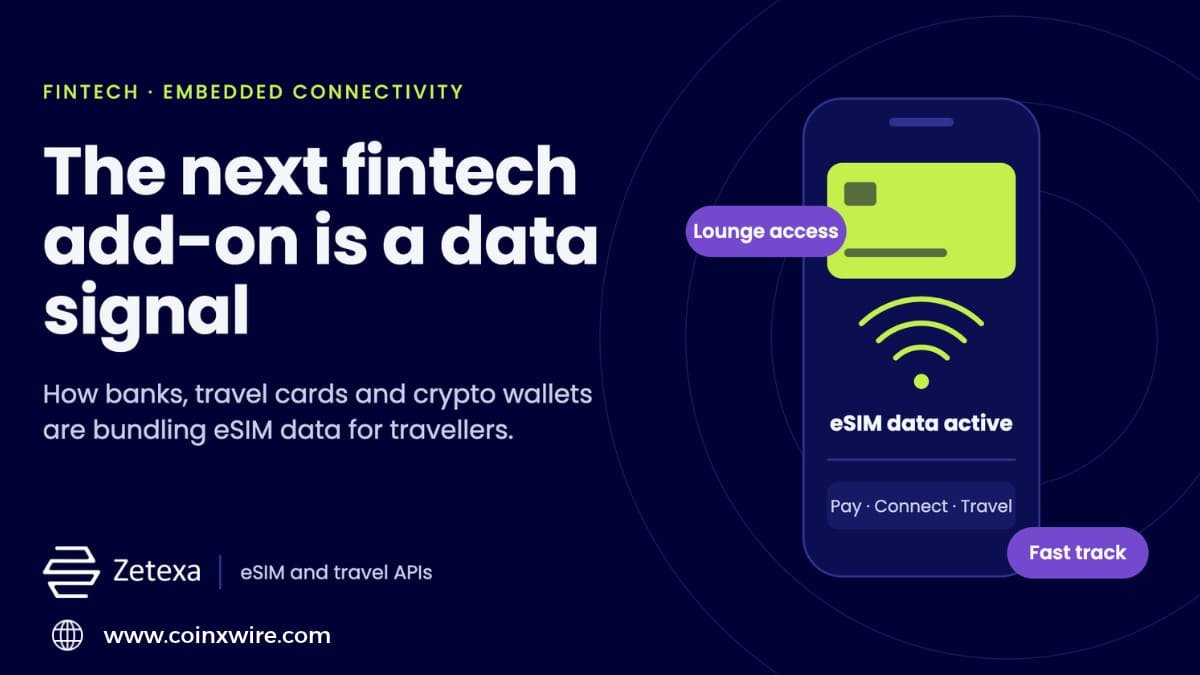
That gap is closing. A growing number of banks, travel cards, booking platforms and crypto wallets are adding mobile data plans directly inside their apps, using embedded eSIM technology. The traveller taps a button, installs a data plan in seconds and stays online without a local SIM or a roaming bill.
This shift has a name: embedded connectivity. And for fintech companies, it is starting to look like the next logical add-on after cards, wallets and insurance. Infrastructure providers such as Zetexa are making it possible for any app to offer it without becoming a mobile operator.
What is Embedded Connectivity in Fintech with Examples?
Embedded connectivity builds financial services into non-financial apps, so users never leave the platform. Examples include paying inside a ridesharing app, choosing Klarna instalments at checkout, receiving merchant loans through Shopify Capital, or adding insurance to a purchase. Juniper Research forecast that buy now pay later would account for just over 50% of the embedded finance market in 2026, while IBS Intelligence projected US embedded finance transactions reaching $7 trillion, about 10% of US financial transactions. Regulated partners handle compliance.
Why Embedded Connectivity Belongs in a Fintech App
Payments run on data. One-time passwords, push approvals, card freezes and balance checks all need a connection. A traveller who loses signal at an airport can’t approve a transaction, which means a failed payment and a frustrated customer.
Connectivity is also a high-frequency need. People check their data every day of a trip. A feature used that often keeps the app open and top of mind, far more than a one-off currency conversion.
Finally, it follows the money. International travel is one of the largest spending moments in a customer’s year. Banks and card issuers already compete for that spend with forex fees, lounge perks and travel insurance. A data plan fits naturally into the same bundle.
How Embedded eSIM Works Inside an App
An eSIM is a digital SIM built into most recent smartphones. Instead of inserting a plastic card, the user downloads a mobile plan as a profile. That profile can be delivered by a QR code or, increasingly, installed directly from within an app.
For a fintech company, the flow looks like this:
- The customer opens the app and picks a destination and data plan.
- The app charges the customer’s card or wallet balance.
- The app calls an eSIM provider’s API, which issues a profile on a partner network.
- The customer installs the profile in a few taps and switches it on when they land.
The fintech never becomes a mobile operator. It works with an eSIM infrastructure provider that handles carrier agreements, profile issuing and network coverage. The app owns the customer experience and the branding; the provider runs the connectivity in the background. This is usually offered as an API integration or a fully white-label setup.
Where Embedded Connectivity in Fintech Fits
- Neobanks and travel cards: Multi-currency cards are built for people abroad. Adding a data plan next to the card’s travel features turns the app into a single travel toolkit: money, payments and signal in one place.
- Crypto cards and wallets: Crypto users are often frequent travellers and digital nomads. A crypto card that also sells data plans, payable from the wallet balance, gives holders a real-world way to spend digital assets.
- Travel booking and buy-now-pay-later apps: A customer who has just booked a flight is the ideal buyer for a data plan. Offering it at checkout, or bundling it into a pay-later plan, adds value at the exact moment of intent.
- Airport and travel ancillaries: Connectivity is often sold alongside other airport services such as lounge access, fast-track security and meet-and-greet. Apps that already sell travel perks can add data with the same integration approach.
The Business Cases of Embedded Connectivity in Fintech
- A new revenue line: Every data plan sold carries a margin, and it needs no lending risk or regulatory capital. For apps with large travelling user bases, that adds up.
- Stickier customers: A traveller who relies on the app for both money and signal is less likely to switch to a competitor mid-trip or after it. Connectivity becomes a reason to keep the app installed.
- Better travel signals: A data purchase tells the app where and when a customer is travelling. With consent, that can power timely offers such as forex alerts, travel insurance or local merchant rewards.
- Differentiation: Cashback and fee-free spending are now standard. Built-in connectivity is still rare enough to stand out in a crowded market.
What to Check Before Launching
Adding connectivity is simpler than becoming a carrier, but the provider’s choice matters. Fintech teams evaluating it usually look at five things:
- Coverages: Plans should work in the destinations your customers actually visit on reliable local networks.
- Integration options: A clean API for in-app purchases, plus white-label options if you want the plans fully under your brand.
- Pricing and margins: Wholesale rates that leave room for a competitive retail price and a healthy margin.
- Support: Travellers need help fast when they can’t connect. Check who handles activation issues and in which time zones.
- Compliance: Payments, data privacy and any telecom rules in your markets should be covered by both sides.
How Zetexa helps fintech and travel brands
Zetexa is a B2B platform built for exactly this shift. It gives banks, card issuers, crypto wallets and travel platforms the infrastructure to sell connectivity and travel services under their own brand, with partners in more than 50 countries.
- eSIM API: Fintech apps can plug Zetexa’s API into their existing flow. Customers browse plans, pay with their card or wallet balance, and install an eSIM without leaving the app. Zetexa handles carrier agreements, profile issuing and network coverage in the background.
- White-label eSIM: Brands that want a fully branded product can launch their own eSIM offering on Zetexa’s platform. The customer sees the bank’s or wallet’s name, not a third party’s.
- Reseller programme: Companies that want to start quickly, without deep integration, can resell Zetexa eSIM plans to their customers and earn on every sale.
- Travel ancillary APIs: Beyond data, Zetexa now offers airport meet-and-greet, lounge access and fast-track services through the same kind of integration. A travel card can offer data, a lounge pass and faster security in one place, turning a payment app into a full travel companion.
For a fintech team, this means a new revenue line and a stronger travel proposition without building telecom capability from scratch.
Conclusion
Fintech has spent a decade absorbing services that used to live elsewhere: cards, insurance, investing and now crypto. Connectivity is a natural next step, because every one of those services stops working without a signal.
For banks, card issuers and travel platforms, embedded eSIM is a low-risk way to earn more from customers’ trips and keep them closer. With platforms like Zetexa providing the eSIM and travel APIs, the barrier to entry is now an integration, not a telecom licence. The apps that move first will be the ones travellers open the moment they land.
FAQs
Que 1. What is embedded connectivity in fintech examples?
Ans. Embedded connectivity means financial services work inside apps people already use. Examples include paying for a ride within a ridesharing app, splitting a purchase into instalments at checkout with Klarna, instant driver payouts on delivery platforms, and insurance offered at the cart page. Buy now pay later is forecast to make up just over 50% of the embedded finance market in 2026.
Que 2. What is embedded finance in banking?
Ans. In banking, embedded finance means a licensed bank offers its products to non-financial companies through APIs. Those companies sell accounts, cards or loans under their own brand, while the bank keeps the licence and compliance duties. This gives banks new distribution. Juniper Research forecast the market would grow from $43 billion in 2021 to over $138 billion in 2026.
Que 3. Types of embedded connectivity in fintech?
Ans. Juniper Research groups embedded finance into five segments: payments, lending, investments, insurance and banking. Payments work inside apps without redirects, lending offers credit at the point of need, investments enable micro-investing, insurance bundles cover with purchases, and banking provides accounts and cards. Embedded insurance premiums were forecast to reach over $10 billion in 2026.
Que 4. Which are the top embedded finance companies?
Ans. No official ranking exists, so this list reflects wide use. Stripe and Adyen lead payments, Marqeta and Galileo power card issuing, Plaid links bank accounts, Klarna and Affirm lead point-of-sale lending, and Unit and Solaris offer banking-as-a-service. US embedded finance transactions were projected to reach $7 trillion in 2026. Always verify licences and financials before partnering.